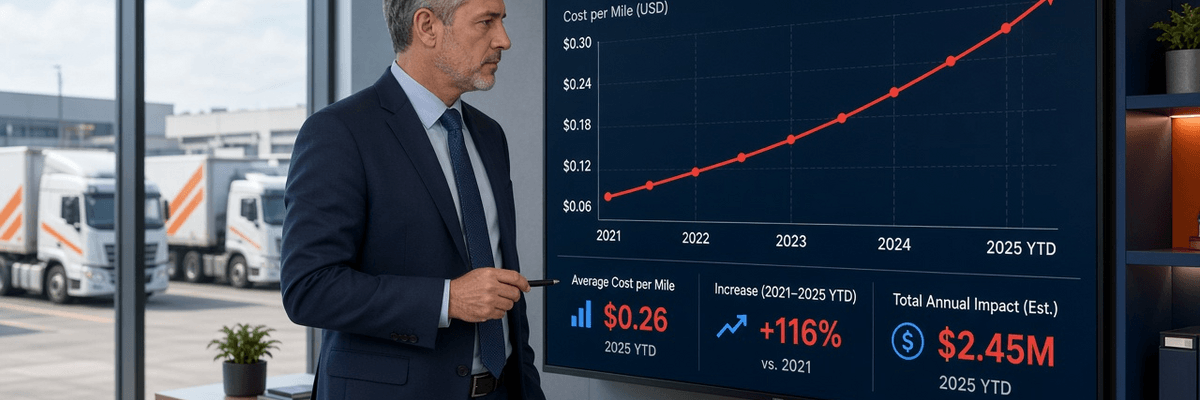
The Bottom Line Up Front: Commercial auto insurance is no longer a predictable line item — it is the fastest-rising cost on most fleet P&Ls, and underwriters are responding by pricing risk directly against the quality of a carrier's documented safety and maintenance program. A carrier that can produce twenty-four months of locked, timestamped, photo-verified digital inspection records at renewal is negotiating from a fundamentally stronger position than one handing a broker a stack of signed paper forms with no independent way to verify when they were actually completed. That same documentation gap is exactly what plaintiff attorneys exploit to build nuclear verdict cases. A strictly enforced electronic DVIR workflow does not just reduce fines — it directly protects two of the largest, least-controllable line items on a fleet's income statement: insurance premiums and litigation exposure. Viewed this way, a well-implemented digital DVIR platform functions as fleet risk management software in its own right, not just a compliance tool.
Key Takeaways: Insurance Premiums, Digital DVIRs, and Litigation Defense
- Commercial auto insurance is structurally unprofitable for carriers, not just expensive for fleets: the line has posted an underwriting loss for 14 consecutive years, which pushes underwriters to scrutinize every renewal application far more aggressively than they did a decade ago.
- Documentation quality is now a pricing input, not a paperwork formality: underwriters increasingly request loss runs alongside proof of a consistently enforced inspection and maintenance program before quoting a renewal.
- Nuclear verdicts (jury awards of $10 million or more) have grown far faster than inflation: and plaintiff attorneys build their negligence arguments around gaps, inconsistencies, or unverifiable dates in a carrier's own maintenance records.
- A locked, role-verified digital inspection record removes the raw material those arguments depend on: it cannot be edited after the fact, which is precisely what both an underwriter and a defense attorney need to see.
Why Commercial Truck Insurance Is at a Breaking Point
Commercial auto insurance premiums are rising because the line of business itself has been unprofitable for insurers for over a decade, and trucking specifically carries an outsized share of the litigation exposure driving that loss — a combination that is pushing rates up industry-wide regardless of any individual carrier's own safety record.
The numbers are not subtle. According to the American Transportation Research Institute's 2026 Analysis of the Operational Costs of Trucking, the average cost to operate a truck reached a record $2.336 per mile in 2025, up 3.4 percent over 2024, and early Q1 2026 data showed insurance premiums specifically jumping 6.4 percent — outpacing nearly every other major cost category except fuel volatility. Repair and maintenance costs rose 8.6 percent over the same period, the largest percentage increase of any line item besides tolls. Fleets are being squeezed from both directions at once: the cost of keeping equipment road-ready is climbing, and the cost of insuring that equipment is climbing faster.
The underlying reason is structural, not cyclical. Commercial auto liability has posted an underwriting loss for 14 consecutive years running, with a $4.9 billion loss in 2024 alone and an industry-wide reserve shortfall that AM Best estimates at $4 to $5 billion. S&P Global projects the commercial auto combined ratio — the percentage of every premium dollar an insurer pays out in claims and expenses — will climb from 104.4 percent in 2026 to 106.3 percent by 2029, meaning insurers are still projected to lose money on this line for years to come even after repeated rate increases. Trucking carries a disproportionate share of that exposure: excess liability coverage for commercial fleets has seen rate increases exceeding 75 percent in recent renewal cycles, and smaller trucking operators now routinely pay more than three times the per-mile insurance cost of large fleets, because they lack the claims history volume that lets a megacarrier smooth out a single bad year.
What this means in practice is that every fleet, regardless of its own safety record, is renewing into a harder market than it was five years ago. The fleets that fare best in that environment are not necessarily the ones with the fewest incidents — they are the ones that can prove, with verifiable evidence rather than a self-reported claim, exactly how their safety and maintenance program actually operates day to day.
Inside the Underwriter's Mind: What a Renewal Application Really Evaluates
A commercial auto underwriter evaluating a fleet's renewal is not primarily reading a maintenance policy document — they are looking for verifiable, dated evidence that the policy described on paper is actually the one being enforced in the yard every single day, and the loss run report is where any gap between the two becomes visible.
Every renewal cycle, an underwriter pulls the fleet's loss run: a claim-by-claim history covering the trailing three to five years, showing what was paid, what is reserved, and what is still open. A pattern of mechanical-failure claims — blown tires, brake-related incidents, lighting-related citations that escalated into a crash — is read very differently depending on what documentation exists alongside it. A fleet that can show the exact inspection record for the vehicle involved, including who inspected it, when, and what was found, is presenting a single, explainable incident. A fleet that cannot produce that record at all is presenting a pattern the underwriter has no way to distinguish from systemic neglect, and pricing models are built to charge a premium for that ambiguity.
Underwriters also increasingly cross-reference a carrier's own submitted materials against public safety data. A motor carrier's FMCSA Safety Measurement System percentiles — including the Vehicle Maintenance BASIC score we cover in depth in our guide to lowering your CSA score through digital DVIRs — are publicly available, and a mismatch between a clean-sounding renewal application and an elevated Vehicle Maintenance percentile is an immediate red flag that either triggers a request for more documentation or simply results in a higher quoted rate. Underwriters are, in effect, running the same due-diligence check that freight brokers run before awarding a load, just with dollars attached to the outcome instead of a load offer.
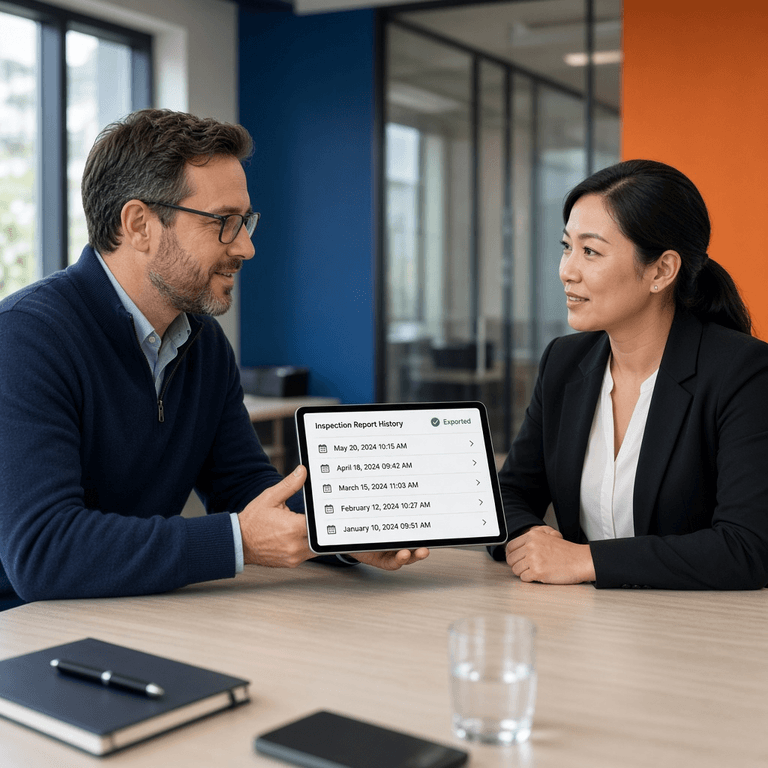
The single most common friction point in this process is timing. A fleet asked to produce twelve months of inspection records for a specific unit involved in a claim, using a paper-based system, is often looking at a multi-day search through filing cabinets or scanned folders with no reliable way to confirm the documents were not altered after the fact. A fleet running a digital DVIR platform can export that exact history — every inspection, every defect classification, every repair sign-off — in minutes, with each record carrying an immutable timestamp the underwriter can trust without a follow-up phone call. That speed and that trustworthiness are not incidental conveniences; they are the two things that most directly determine whether a renewal negotiation goes smoothly or drags into a defensive back-and-forth that rarely ends in the carrier's favor.
High-Risk vs. Low-Risk: The Fleet Profile Underwriters Actually Price
Underwriters do not evaluate fleets as uniformly good or bad risks — they build a composite risk profile from several concrete, observable characteristics of how a carrier actually manages its inspection and maintenance program. The table below lays out the two ends of that spectrum as underwriters themselves tend to describe it during renewal conversations.
| Underwriting Factor | High-Risk Profile | Low-Risk Profile |
|---|---|---|
| Inspection record format | Paper logs, often stored on-site with no offsite backup | Cloud-based digital archive, accessible and exportable on demand |
| Defect resolution timeline | Irregular; no visible timestamp between defect and repair sign-off | Near-instant closure with timestamped repair verification |
| Record integrity | Editable after the fact; no independent verification of completion date | Locked at close; timestamp cannot be altered retroactively |
| Inspection consistency | Sporadic; some units or routes show large documentation gaps | Every unit, every trip, with no missing records in the archive |
| Evidence supporting a defect finding | A checked box with a driver signature and no supporting detail | Timestamped photo evidence tied to a specific defect classification |
| CSA Vehicle Maintenance BASIC alignment | Elevated percentile with no clear improvement plan on file | Documentation directly correlated with a low or improving percentile |
| Renewal submission speed | Days to weeks to compile requested records manually | Minutes to export a filtered, audit-ready inspection history |
Notice that none of these factors are about whether a fleet has ever had an accident — every fleet eventually will. They are about whether the fleet can prove, with evidence an underwriter cannot easily dispute, that its stated safety program is the one actually operating in the yard. A carrier that moves even two or three rows of this table from the high-risk column to the low-risk column is not just avoiding a rate increase; it is giving its broker concrete, defensible material to negotiate a better renewal with, rather than simply accepting whatever the market-wide hardening trend dictates.
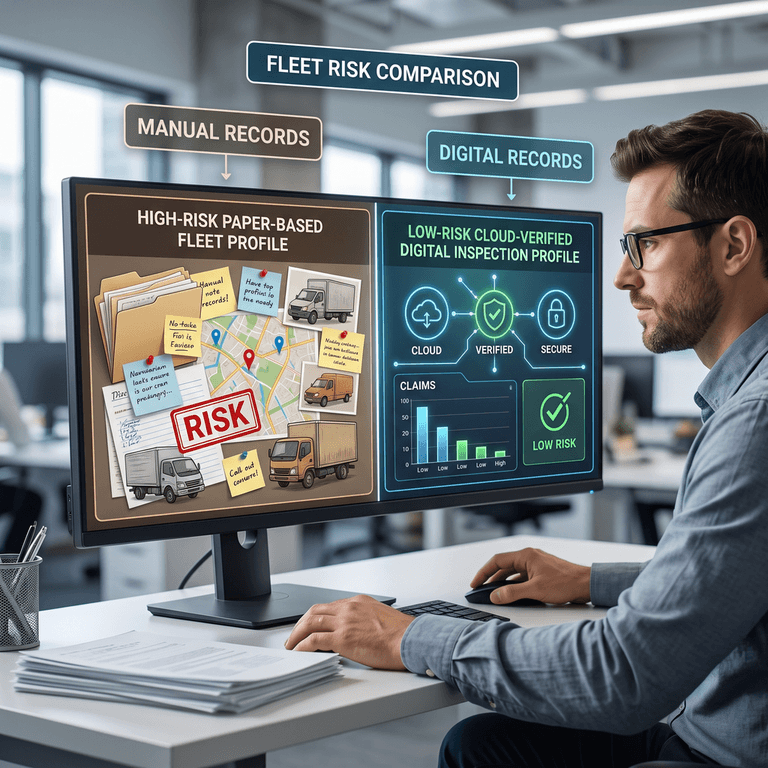
Could an incomplete inspection record cost you your next policy renewal — or your defense in a lawsuit? Prevent both with PTI4YOU: locked, timestamped digital DVIRs that give underwriters and defense attorneys the same thing — proof.
The Nuclear Verdict Threat: How Plaintiff Attorneys Attack Fleet Negligence
A nuclear verdict is a jury award of $10 million or more, and in trucking litigation these awards have grown far faster than inflation over the past decade because plaintiff attorneys have refined a specific playbook: build a narrative of systemic negligence around gaps, inconsistencies, or unverifiable claims in a carrier's own maintenance and inspection documentation.
The scale of this trend is well documented. ATRI's original research on nuclear verdicts in trucking found that between 2010 and 2018, the average size of verdicts over $1 million against motor carriers grew from roughly $2.3 million to $22.3 million — a 967 percent increase — while standard inflation grew at just 1.7 percent annually and healthcare costs at 2.9 percent. More recent research cited in ATRI's Trucking Litigation forensic analysis found the median nuclear verdict reached $36 million in 2022, per the U.S. Chamber of Commerce Institute for Legal Reform, roughly 50 percent higher than the 2013 median. None of that growth is explained by crashes becoming more severe; it is explained by a litigation environment that has become significantly more aggressive and better funded.
The tactic driving much of this growth is often described in the industry as "reptile theory": rather than arguing narrowly about the specific mechanics of a single crash, plaintiff attorneys build a broader case that the carrier's entire safety culture is negligent, using any documentation gap as proof. A missing inspection record, a repair log with no verifiable timestamp, or a DVIR that was clearly signed in bulk at the end of a shift rather than completed component-by-component becomes exhibit evidence that the carrier's stated safety program was, in the plaintiff's framing, a fiction. Once a jury accepts that framing, the specific facts of the crash itself often become secondary to the emotional weight of "this company doesn't actually check its trucks."
This is precisely why a fleet's own record-keeping practices are now a litigation risk category, independent of how well-maintained the equipment physically is. A truck that received a genuinely thorough pre-trip inspection, but whose paper DVIR cannot be independently verified as having been completed on the date and by the person it claims, hands a plaintiff attorney the exact gap the reptile theory playbook is built to exploit — regardless of whether the inspection actually happened as described.
The Legal Shield: How Role-Based Locking Defends Against Spoliation Claims
The strongest defense against a negligence argument built on documentation gaps is a workflow architecture that makes it structurally impossible to alter a record after it was created, reviewed, and closed — which is exactly what a role-based digital DVIR system with a hard lock on completed reports is designed to do.
A three-role chain of custody: driver, inspector, reviewer
PTI4YOU structures every inspection record through three distinct roles: the driver who identifies and photographs a defect, the inspector or mechanic who performs and documents the repair, and the reviewer who verifies and formally closes the record. This mirrors the same driver-mechanic-driver signature discipline required under 49 CFR 396.11, which we cover in detail in our guide to the FMCSA 396.11 three-signature cycle, extended with an explicit reviewer role. In a litigation context, that three-role chain of custody matters enormously: a defense attorney can show a court exactly who touched the record, in what order, and when — the same standard of evidentiary integrity courts expect from any business record offered as proof.
The record lock: why editable history is a liability, not a convenience
Once a report has been reviewed and closed, PTI4YOU's record lock — the same mechanism we describe as the lock_date feature in our companion piece on CSA score protection — freezes it against any further modification. This is not a minor technical detail; it is the specific feature that neutralizes a spoliation argument before it can be raised. Spoliation is the legal claim that evidence relevant to a case was destroyed, altered, or improperly withheld, and courts can instruct a jury to assume the missing or altered evidence was unfavorable to the party who controlled it. A carrier that stores inspection records in an editable spreadsheet or a paper file with no independent verification of completion date is structurally unable to prove a record was not altered after a crash occurred. A carrier running a system that mathematically prevents that alteration — where the closed record's timestamp is enforced by the platform itself, not by an honor system — can produce evidence a court has no basis to question.
Photo evidence as an independent witness
Mandatory, timestamped photo evidence of specific components adds a second, independent layer of proof beyond the written record itself. A photograph of a brake component, a tire, or a coupling device, captured at the moment of inspection and attached permanently to a locked record, functions in a courtroom the way a credible eyewitness would — it corroborates the written finding with evidence that is very difficult to fabricate convincingly after the fact. Fleets that have made this shift from checkbox-only inspections to photo-documented ones are addressing the same underlying integrity problem we cover in our guide to stopping pencil-whipped inspections: a signature alone proves nothing about whether a genuine inspection occurred, while a timestamped photo of the specific component in question is difficult to dispute.
Build an Undeniable Chain of Evidence
PTI4YOU's three-role workflow and hard record lock give every completed DVIR a tamper-evident timestamp — the exact evidentiary standard both insurance underwriters and defense attorneys are looking for.
Start your 15-day free trial today. No credit card required.
Start Your 15-Day Free Trial – No Credit Card RequiredZero setup fees. Zero hardware. 25-minute driver onboarding.
From Data to Dollars: Presenting Your Inspection Records to Your Broker
Having audit-ready inspection records is only half the equation; the other half is knowing how to package and present that history to your insurance broker in a way that actually moves the underwriter's pricing decision, rather than simply sitting unused in a database.
Export the right window, not everything
Most underwriters care most about the trailing 12 to 24 months, aligned with how loss runs and CSA Vehicle Maintenance data are themselves evaluated. PTI4YOU's inspection report files can be filtered and exported by date range, unit, and defect classification, letting a fleet manager produce exactly the window a broker requests — typically a full history for any unit involved in an open claim, plus a fleet-wide summary showing overall inspection completion rates and defect resolution times.
Lead with resolution speed, not just inspection volume
A broker presenting a fleet's safety story to an underwriter is more persuasive citing a specific, verifiable metric — average time from defect identification to repair sign-off — than a vague claim of "we inspect every truck every day." A locked, timestamped record makes that metric provable rather than aspirational, and it directly answers the underwriting question raised earlier: does the maintenance policy on paper match what actually happens in the yard.
Pair the export with your CSA Vehicle Maintenance trend
Because underwriters routinely pull public SMS data independently, a broker is in a stronger position presenting a fleet's own inspection export alongside a Vehicle Maintenance BASIC trend line showing measurable improvement, rather than letting the underwriter discover a mismatch on their own. A fleet whose weighted points are trending down because new violations have stopped accumulating — the exact mechanism detailed in our guide to lowering your CSA score with digital DVIRs — is telling a coherent, corroborated story that a broker can walk into a renewal meeting with confidence.
Do not wait for a claim to build this file
The single biggest mistake fleets make is treating this documentation package as something to assemble reactively, after a claim or a difficult renewal notice arrives. Reputation and documentation compound over time, in the same way our guide on protecting fleet reputation from chameleon-carrier scrutiny describes for safety ratings generally — a fleet with two years of consistent, locked records at renewal time is negotiating from an entirely different position than one scrambling to produce six months of clean data after a bad claim already put the underwriter on alert.
Calculate Your Potential Insurance Savings With PTI4YOU
There is no single universal percentage every fleet will save on its commercial auto premium by digitizing its inspection program, and any claim promising an exact guaranteed figure should be treated skeptically — but the underlying cost mechanics are concrete enough to build a directionally honest estimate specific to your own fleet.
Insurance brokerages that work with usage-based and safety-documentation underwriting programs commonly describe a directional range, often cited in the neighborhood of 5 to 25 percent off a commercial auto premium, split between two components: a smaller enrollment-style credit simply for having verifiable, consistently generated data, and a larger performance-based credit for demonstrating sustained, documented safety practices over a full policy term, typically six to twelve months. The exact figure your fleet would see depends entirely on your specific carrier, your loss history, and your fleet size — but the formula below lets you build your own working estimate rather than relying on an unverifiable marketing claim.
| Input | Illustrative Value | Notes |
|---|---|---|
| Fleet size | 40 power units | Sample fleet for illustration only |
| Estimated annual commercial auto premium | $14,000 per truck | Varies significantly by state, commodity, and radius of operation |
| Fleet-wide annual premium (before credits) | $560,000 | 40 × $14,000 |
| Illustrative documentation credit range | 5% – 15% | Conservative end of commonly cited brokerage ranges; confirm with your own broker |
| Estimated annual premium impact | $28,000 – $84,000 | 560,000 × 5% and × 15%, respectively |
To build your own version of this table: pull your current fleet-wide annual premium from your most recent policy declaration, multiply it by a conservative range you confirm directly with your broker rather than a vendor's marketing figure, and use the result as a starting point for a renewal conversation — not as a promised outcome. The value of a digital DVIR program is not that it guarantees a specific discount; it is that it gives your broker verifiable, exportable evidence to make the strongest possible case for whatever discount your specific carrier is willing to offer, in a market where undocumented fleets increasingly get no negotiating room at all.
Calculate Your Potential Insurance Savings With PTI4YOU
Build your fleet's own documentation-driven premium estimate and see exactly what a locked, exportable inspection archive would let your broker bring to your next renewal.
Start your 15-day free trial today. No credit card required.
Calculate Your Potential Insurance Savings with PTI4YOUZero setup fees. Zero hardware. 25-minute driver onboarding.
The Fleet Manager's Blueprint for Acing an Insurance Renewal Audit
Use this checklist in the 90 days before your next commercial auto policy renewal to build the strongest possible documentation package for your broker.
- Pull your current loss run report. Request the trailing 3–5 year claim history from your carrier and review it for patterns before your underwriter does.
- Export 12–24 months of inspection history for every unit with an open or recent claim. Filter by unit number and date range so the export directly addresses the specific vehicles a loss run flags.
- Confirm every exported record shows a locked timestamp. An underwriter or defense attorney needs to see that the completion date cannot have been altered after the fact.
- Calculate your average defect-to-repair resolution time. This single metric is often more persuasive to an underwriter than a raw inspection count.
- Pull your current FMCSA Vehicle Maintenance BASIC percentile. Know this number before your underwriter finds it independently, and be ready to explain any recent trend.
- Identify and document any recurring defect patterns. A unit or route generating repeat issues is a red flag if unaddressed, but a documented remediation plan turns it into evidence of active risk management.
- Verify photo evidence exists for high-severity inspection points. Brakes, tires, steering components, and coupling devices carry the most weight in both CSA scoring and litigation risk.
- Brief your broker before the underwriter's questions arrive. Walk your broker through the documentation package proactively so they can present it, rather than reacting defensively to an underwriter's follow-up request.
- Confirm your driver qualification files are current alongside your inspection records. Underwriters and plaintiff attorneys alike evaluate maintenance documentation as part of a broader safety management picture, not in isolation.
- Set a recurring 90-day review cycle, not a once-a-year scramble. Treat renewal preparation as a continuous discipline so the next cycle starts from an already-strong position.
None of these steps require new hardware, a change to dispatch operations, or a new insurance carrier. They require a documentation system that makes producing this exact package a matter of minutes rather than days — which is the specific gap between fleets that walk into a renewal meeting with leverage and fleets that accept whatever the market-wide hardening trend dictates.
Frequently Asked Questions
Do commercial truck insurance underwriters review daily maintenance logs?
Absolutely. During annual policy renewals, underwriters increasingly demand detailed loss runs accompanied by proof of a strict, documented preventive maintenance program to accurately assess carrier risk before pricing a policy.
How does a digital DVIR protect a fleet from catastrophic nuclear verdicts?
In post-crash litigation, immutable digital records of pre-trip inspections and completed repairs prove the motor carrier was not negligent regarding vehicle safety, neutralizing a plaintiff attorney's primary negligence argument before it reaches a jury.
What is considered a nuclear verdict in trucking litigation?
The American Transportation Research Institute defines a nuclear verdict as a jury award of $10 million or more. Research from the U.S. Chamber of Commerce Institute for Legal Reform found the median nuclear verdict reached $36 million in 2022, roughly 50 percent higher than the 2013 median, and ATRI's own trucking litigation database recorded a near-tenfold jump in cases exceeding $1 million between the early and late 2010s.
How much can documented safety and inspection programs actually lower insurance premiums?
There is no single guaranteed figure, and any vendor quoting an exact universal percentage should be treated with caution. Fleet insurance brokerages that work with usage-based and safety-documentation programs commonly describe a directional range, often cited between roughly 5 and 25 percent off commercial auto premiums, split between an enrollment credit for having verifiable data at all and a larger performance credit for sustained, consistent documentation over a full policy term. The exact figure always depends on the specific carrier, program, fleet size, and loss history.
What is a loss run report, and why do underwriters request it at renewal?
A loss run report is a carrier-generated history of every claim filed against a policy, including open, closed, and reserved amounts. Underwriters request it at renewal to calculate a fleet's actual loss ratio and to look for patterns, such as repeated mechanical-failure claims, that suggest the maintenance and inspection program described in an application is not being enforced in daily operations.
Can insurance underwriters see a carrier's CSA Vehicle Maintenance BASIC score?
Yes. A motor carrier's FMCSA Safety Measurement System percentiles, including the Vehicle Maintenance BASIC, are publicly available data, and commercial auto underwriters routinely pull this information as part of standard risk assessment alongside the carrier's own submitted loss runs and safety documentation.
What is spoliation of evidence, and how can it hurt a fleet in a lawsuit?
Spoliation is the destruction, alteration, or loss of evidence relevant to litigation. If a plaintiff attorney can show that a carrier's maintenance or inspection records were edited after the fact, or that records that should exist cannot be produced, a court can instruct the jury to assume the missing evidence was unfavorable to the carrier, which can be devastating in a negligence case regardless of what actually happened to the vehicle.
How far in advance should a fleet prepare its documentation before an insurance renewal?
Most brokers and telematics-linked underwriting programs recommend beginning the documentation review roughly 90 days before a policy renewal, which provides enough time to pull loss runs, export inspection history, identify and remediate any recurring defect patterns, and assemble a clean submission package rather than reacting to an underwriter's questions after the quote has already been priced.
Conclusion: Documentation Is the Asset That Protects the Rest of Your Balance Sheet
Commercial auto insurance premiums and nuclear verdict exposure are two of the largest, least predictable line items on a trucking company's income statement, and both are being driven by the same underlying market forces: a litigation environment that has grown far faster than inflation, and an insurance market that has been unprofitable for over a decade and is pricing every renewal more conservatively as a result. A fleet cannot control those market forces. It can control whether its own inspection and maintenance program produces the kind of evidence an underwriter can price with confidence and a defense attorney can put in front of a jury without hesitation.
That evidence is not a training slogan or a safety culture statement — it is a locked, timestamped, photo-verified digital record that cannot be edited after the fact, generated by a role-based workflow that shows exactly who touched it and when. Fleets that build this documentation discipline before a claim, a lawsuit, or a difficult renewal notice arrives are the ones walking into those conversations with leverage instead of exposure.
Protect Your Premiums and Your Litigation Defense in One System
Give every completed inspection a locked, audit-ready record the moment it's closed — the exact evidence your broker needs at renewal and your defense counsel needs in court.
Start your 15-day free trial today. No credit card required.
Start Your 15-Day Free Trial – No Credit Card RequiredZero setup fees. Zero hardware. 25-minute driver onboarding.
Official Sources and Further Reading
- American Transportation Research Institute — 2026 Analysis of the Operational Costs of Trucking
- American Transportation Research Institute — Understanding the Impact of Nuclear Verdicts on the Trucking Industry
- Commercial Auto Posts $4.9B Loss for 14th Straight Year — Underwriting Market Analysis
- eCFR — 49 CFR 396.11: Driver Vehicle Inspection Reports
This article reflects publicly available industry cost, underwriting, and litigation data as of September 26, 2026. Insurance premium credits and discount ranges cited are directional industry patterns, not a guarantee from PTI4YOU or any specific insurance carrier; fleets should confirm exact figures with their own broker and underwriter.